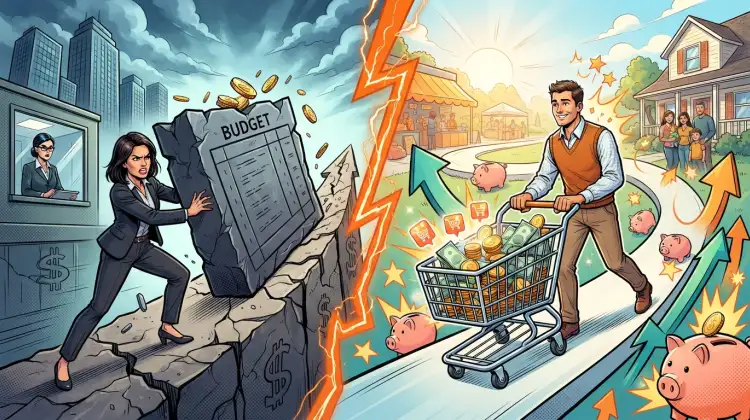
If you have ever tried to get a handle on your money, you have probably run into two terms that sound interchangeable: a budget and a spending plan. They overlap, but they are not the same thing. A budget is typically a set of limits on categories of spending, while a spending plan is a forward-looking map of where your money will go before the month begins. Understanding the difference matters because the approach you choose affects whether you stick with it. According to the Federal Reserve's Economic Well-Being of U.S. Households report, a meaningful share of adults say they could not cover a $400 emergency expense with cash, which makes a workable plan for monthly cash flow more than an academic exercise.
What Is a Budget?
A budget is a framework of limits. You decide how much you are willing to spend on groceries, dining out, transportation, and so on, then track actual spending against those caps. The emphasis is on restraint: staying under the line. Many people build budgets around percentages, such as the popular 50/30/20 rule, which allocates 50% of take-home pay to needs, 30% to wants, and 20% to savings and debt repayment.
Budgets are useful when your problem is overspending in specific categories. They give you a clear signal when you cross a threshold. The downside is that a budget can feel punitive. If your spending is irregular, a rigid cap may be unrealistic, and people often abandon budgets after a few months when reality does not match the plan.
What Is a Spending Plan?
A spending plan starts from the same raw material, your income and expenses, but flips the emphasis. Instead of asking "How little can I spend here?" it asks "Where do I want this money to go?" You assign every dollar a job at the start of the month, including savings, debt payments, and fun money. The plan is proactive rather than restrictive.
This is the approach behind zero-based budgeting methods and many popular apps. A spending plan treats savings and investments as line items, not leftovers. If you earn $4,800 a month, the plan accounts for all $4,800 before the month starts, including a transfer to a high-yield savings account or a brokerage account. The goal is intentionality, not deprivation.
Key Differences Between a Spending Plan and a Budget
- Direction: A budget looks backward at limits and compares spending to caps. A spending plan looks forward and assigns income before it arrives.
- Mindset: Budgets emphasize restriction. Spending plans emphasize purpose and priorities.
- Flexibility: Budgets often break when an unusual expense appears. Spending plans can be adjusted month to month as circumstances change.
- Savings treatment: In many budgets, savings is whatever remains. In a spending plan, savings is a funded category from the start.
- Tracking: Both require tracking, but a budget tracks against limits while a spending plan tracks against assignments.
Which Approach Fits Your Situation?
Choose a budget if you need guardrails in a few problem areas, such as food delivery or online shopping, and you already have a stable income. A simple category cap can be enough to change behavior.
Choose a spending plan if your income varies, if you are juggling multiple goals like an emergency fund and credit card payoff, or if past budgets have felt too rigid. Freelancers and commission-based workers often prefer spending plans because they can rebuild the plan each month around actual expected income.
In practice, most households blend the two. You might set limits on discretionary categories while assigning every dollar of income to a purpose. That hybrid gives you both the guardrails of a budget and the intentionality of a spending plan.
How to Build Either One in Five Steps
- List your net income. Use take-home pay after taxes and payroll deductions, not gross salary.
- Total your fixed costs. Rent or mortgage, utilities, insurance, minimum debt payments, and transportation.
- Estimate variable costs. Review the last two or three months of bank and card statements to get realistic grocery, gas, and personal spending figures.
- Assign the remainder. Fund savings and debt payoff before discretionary spending. Even $50 a month toward an emergency fund builds a buffer.
- Review weekly and adjust monthly. A plan that is never checked is just a wish list. A short weekly review catches drift early.
Keep in mind that the Consumer Financial Protection Bureau recommends building an emergency fund that can cover several months of expenses, which is easier to achieve when savings is a planned line item rather than an afterthought.
What to Remember
A budget sets limits; a spending plan assigns purpose. Neither is inherently better, and the right choice depends on your income pattern, your spending habits, and what has worked for you in the past. The most effective system is the one you will actually review each month. Start with a realistic picture of your cash flow, fund savings deliberately, and adjust as life changes.







